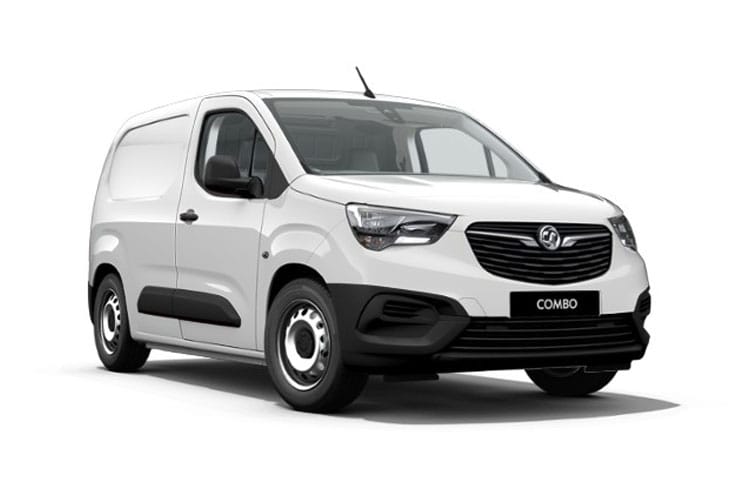
Vauxhall
Combo Cargo
L2H1 2300 1.5 Turbo D 100 Dynamic
Bad Credit Van Leasing
Yes, you can lease a van with bad credit. Approval depends on three things: how recent the credit issue is, the size of your initial rental, and whether the lease is personal or business. We work with specialist underwriters who consider applications that mainstream lenders decline.
The starting point
Who we help
Your options
You still have access to a variety of leasing formats, including:
Pay a fixed monthly fee over an agreed term and return the van at the end.
Explore →Own the vehicle at the end of the agreement with a final balloon payment.
Explore →Save money by leasing a high-quality used van with lower monthly costs and quicker approval.
Explore →The process
When applying for van leasing with bad credit, the approval process may involve:
CCJs and low scores
The range
You’ll still have access to a wide range of vans, including:
great for city-based trades and local deliveries. View Small Van Leasing Options.
Browse small vans →ideal for balanced storage and mobility.
Browse medium vans →for businesses that need serious cargo space.
Browse large vans →for specialist needs.
Browse pickups, crew vans, tippers, and dropsides →
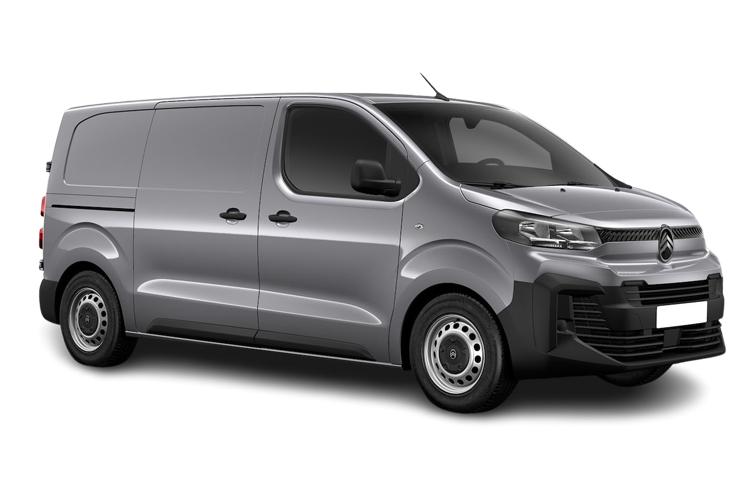
Vauxhall
L2H1 2300 1.5 Turbo D 100 Dynamic

Ford
240 L2 2.0TDCi EcoBlue Trend 122 Auto

Ford
320 L2 2.0TDCi 136 EcoBlue Leader

Citroën
2.0 BlueHDi M Enterprise EAT8

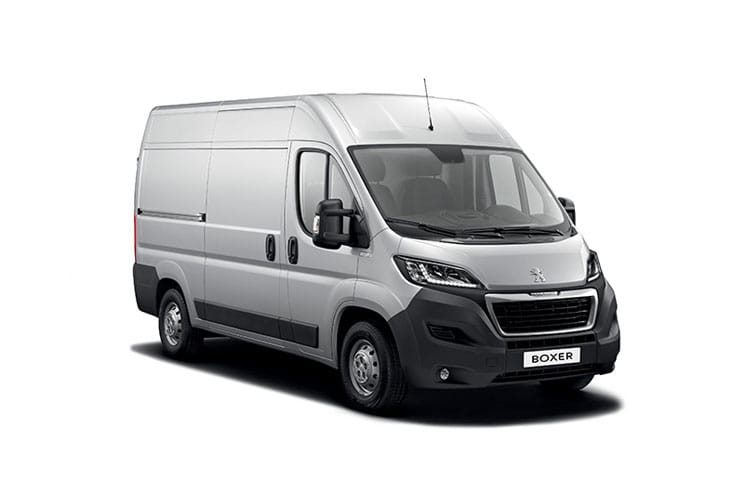
Peugeot
333 L1H1 2.2 BlueHDi 120 S 3000


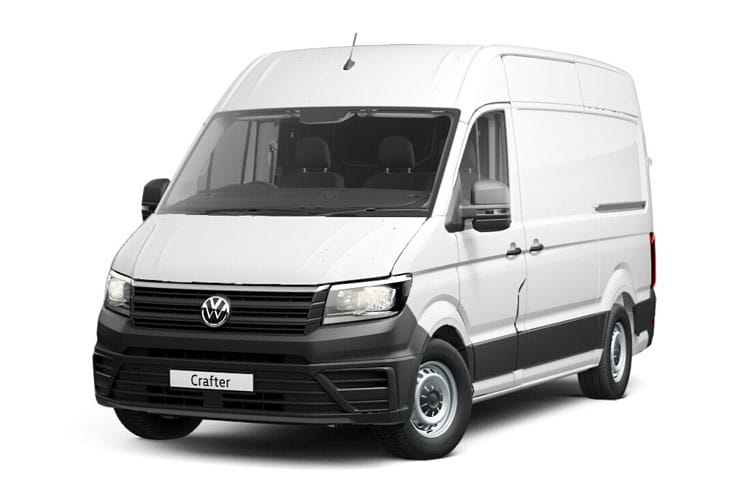
VW
CR35 L3H3 Medium Wheel Base 2.0 TDI 102 Trendline

Why it works
New businesses
Applying
Applying is quick and confidential. Here’s how to get started:
FAQs
Specialist leasing brokers like VanLeasing.com are usually your best option if you have no credit history or a thin file. We work with funders who assess applications individually rather than relying purely on automated credit scores. For new businesses with no trading history, funders typically look at the director’s personal credit, the nature of the business, and any evidence of income (contracts, invoices, or bank statements). A higher initial payment – usually 6 to 9 months – is often required to offset the risk. Having a clean personal credit file (even if thin) significantly improves your chances, as does being able to show that you have regular income coming in.
Yes – it’s often possible to lease a van even with a CCJ, defaults, or an IVA on your credit file. The key factors funders look at are how recent the adverse credit event was, how much it was for, and whether it’s been satisfied or is still outstanding. Generally, satisfied CCJs over 12 months old and defaults over 6 months old are viewed more favourably. An active IVA can be more challenging, but some specialist funders will still consider your application if payments are up to date. You may need to put down a higher initial rental (typically 6–9 months instead of 3), and the choice of vehicles may be more limited, but approval is often achievable. At VanLeasing.com, we work with multiple funders who specialise in adverse credit, so we can submit your application to the one most likely to approve it.
Absolutely. We specialise in helping customers who have been turned down before.
Unlike some other leasing companies, VanLeasing.com doesn’t rely solely on your credit score to determine your eligibility. We understand that life is complex, and a single number doesn’t define your financial responsibility. Our flexible approach means we consider a variety of factors when assessing your application. While a better credit score can lead to more favourable terms, we’re here to work with you, no matter where your credit score stands.
For most people with adverse credit, leasing works out more affordable. The interest rates on hire purchase or personal loans for applicants with poor credit tend to be significantly higher than the additional cost built into a specialist lease. Leasing avoids the large upfront cost of buying, preserves your working capital, and gives you a brand new vehicle with a full manufacturer’s warranty and fixed monthly payments.
Our lending panel considers a range of credit situations, including County Court Judgements (CCJs), defaults, late or missed payments, Individual Voluntary Arrangements (IVAs), debt management plans, thin credit files, and low credit scores. Previous bankruptcy may also be considered depending on when the discharge occurred. Each case is assessed on its individual merits.
The initial rental for new businesses and adverse credit applicants is typically higher than the standard three months upfront. Most agreements in this category require between six and nine months’ initial rental. For example, on a monthly payment of £350, you would pay between £2,100 and £3,150 upfront. The exact figure depends on your credit profile, the vehicle, and which lender you’re placed with.
Yes. We work with a panel of specialist lenders who consider applications from drivers and business owners with adverse credit, including CCJs, defaults, missed payments, and low credit scores. Each application is assessed individually on affordability and current circumstances, not just your credit score. You may need a higher initial rental, but many applicants who’ve been turned down elsewhere are able to lease through us.